When a Company’s Value Falls After an Estate Freeze: Is a Refreeze the Answer?
An estate freeze is usually designed around the expectation that a business will grow. The owner exchanges growth-oriented shares for fixed-value preferred shares, while new common shares are issued to the next generation or a family trust. If the company’s value later falls below the redemption amount of the preferred shares, however, the freeze may no longer be working as intended. A refreeze can reset the value hurdle, but it is not simply a matter of changing the number attached to the preferred shares.
How a freeze can become underwater
Assume a company’s equity value was $20 million when its owner completed an estate freeze. The owner received preferred shares with a $20 million redemption amount, and a family trust subscribed for common shares intended to participate in future growth. If the company’s equity value later falls to $15 million, the common shares may have little or no current value. If the business recovers, its value may first accrue to the preferred shares until their redemption amount is reached. The intended growth shareholders may therefore wait longer than expected before sharing in the recovery.
A refreeze may address this mismatch by exchanging the old preferred shares for new fixed-value preferred shares based on the company’s current fair market value (FMV), while leaving the existing growth shares in place. In the simplified example, resetting the preferred-share value to $15 million would allow future value above that amount to accrue to the growth shares. The actual value of each share class depends on its legal rights, restrictions, ranking and other relevant facts, so the company’s overall value is not a substitute for valuing the shares themselves.
The legal steps matter
A direct refreeze is commonly structured as a share exchange within the same corporation under section 86, if the statutory conditions are met. Another possibility is a transfer of the old shares to a taxable Canadian corporation under subsection 85(1), generally with a joint election. The correct approach depends on the transaction’s legal form and the rights attached to the shares (Income Tax Act, section 86; Income Tax Act, section 85).
A direct exchange should also be distinguished from a “thaw and refreeze.” A thaw may involve redeeming the old preferred shares, exchanging them back into another class of shares, or taking other steps before implementing a new freeze. Each step needs its own tax analysis. For example, a redemption may create a deemed dividend under subsection 84(3), while a later subscription for new shares is a separate transaction and may create additional tax consequences.
Valuation is the hinge
The new preferred shares need a defensible FMV. A genuine business downturn, loss of a major customer, weaker earnings or changes in financing conditions may explain a decline. By contrast, dividends on junior shares or excessive compensation that reduce the value of the freeze shares can raise concern that value was shifted before the refreeze. The CRA’s administrative position is generally favourable where the decline is genuine, no corporate assets have been stripped, and the new preferred shares have an FMV equal to the old preferred shares immediately before the exchange. That position is fact-specific, not a statutory safe harbour (2010 STEP/CRA Roundtable response).
The rollover provisions also contain rules addressing benefits intended for related people. Depending on the structure, subsections 86(2) or 51(2), or paragraph 85(1)(e.2), may apply where the value given up exceeds the value received and the shortfall can reasonably be regarded as a benefit intended for a related person. A valuation shortfall does not automatically establish that intention, but an adverse result can include an immediate income inclusion or capital gain (Income Tax Act, section 86; Income Tax Act, section 85).
A contemporaneous valuation should explain the assumptions and evidence behind the conclusion, including the company’s financial condition, earnings outlook, industry circumstances, asset base and share rights. The CRA’s business-equity valuation guidance describes factors relevant to closely held companies (CRA Information Circular IC89-3). A carefully drafted price adjustment clause can help address a later valuation correction, but it cannot replace a genuine effort to determine FMV. The CRA says it expects a bona fide FMV intention, a fair and reasonable valuation method, agreement to accept a value ultimately determined by the CRA or a court, and an actual payment, refund or adjustment of the resulting difference (CRA Income Tax Folio S4-F3-C1).
A 2026 Tax Court decision, Goudreau c. Le Roi, is relevant to this valuation discussion, but it arose from an estate freeze rather than a refreeze. The Court’s analysis supports the narrower point that a valuation shortfall does not, by itself, establish an intended benefit under paragraph 85(1)(e.2), particularly where the parties made a good-faith effort to transact at FMV and their documents included an effective adjustment mechanism. It should not be treated as approval of every refreeze or as a substitute for transaction-specific valuation and documentation (McCarthy Tétrault’s case analysis).
Check the original freeze for corporate attribution
The most consequential issue may come from the original freeze rather than the new one. Subsection 74.4(2) can attribute a deemed interest amount to an individual who transferred property to a corporation where one of the main purposes was to reduce the individual’s income and benefit a designated person, subject to the section’s conditions and exceptions. The corporation’s small business corporation status and the identity and rights of trust beneficiaries can affect the analysis (Income Tax Act, section 74.4).
Importantly, a refreeze may not reset the historic “outstanding amount” used in that calculation. The CRA has stated that shares received on a subsequent refreeze do not reduce the amount, and that a later cash redemption of refrozen shares reduces it only to the extent of the FMV of the shares redeemed. If the other statutory conditions continue to be met, the original attribution exposure can therefore persist even after all refrozen preferred shares have been redeemed; any cash redemption should also be modelled for a possible deemed dividend (CRA document 2020-0860961C6).
Any related trust restructuring requires separate analysis. Trust distributions or transfers may engage the 21-year deemed disposition rule, other trust-distribution provisions, the general anti-avoidance rule and mandatory disclosure requirements. At the 2026 STEP Canada/CRA Roundtable, the CRA described a limited administrative position for certain trust refreeze or share-transfer transactions that were not substantially similar to designated transactions. That response is not a blanket clearance for trust reorganizations (2026 STEP Canada/CRA Roundtable, Question 9).
Other consequences should not be overlooked
Preferred shares issued on a refreeze may be taxable preferred shares. Dividends, including certain deemed dividends, can therefore raise Part VI.1 tax for the corporation. The annual dividend allowance and excluded-dividend rules may reduce or eliminate the tax in some cases, but their availability depends on the share ownership and relationships involved, including who benefits from a trust (Income Tax Act, Part VI.1; Income Tax Act, section 191.1).
The refreeze may also affect paid-up capital, future tax-free distributions, the owner’s access to corporate liquidity, creditor arrangements, and the estate plan. A lower redemption amount can change the resources available to the owner or the owner’s estate if the company later recovers in value. Corporate articles, shareholder agreements, trust terms, elections and minute-book records should be reviewed before the transaction is implemented.
A practical pre-refreeze review
Before proceeding, the owner and professional advisors should confirm:
- Current value: Is there a supportable, contemporaneous valuation of the company and the relevant share classes?
- Cause of decline: Is the reduction in value supported by operating or market evidence, rather than value being shifted out of the corporation?
- Original tax history: Did the original freeze involve section 74.4, and does the corporation qualify as a small business corporation for the relevant period?
- Transaction design: Is the proposal a direct refreeze or a sequence of redemptions, exchanges and new subscriptions, and what are the tax consequences of each step?
- Share and trust terms: Do the articles, share rights and trust documents support the intended result, and are trust-distribution, 21-year and disclosure issues addressed?
- Owner’s needs: Does the owner still rely on the original preferred-share value for retirement, liquidity, creditor or estate planning?
A refreeze can restore the intended path for future growth when a company’s value has genuinely declined. The decision should not be made on valuation alone, however. The original freeze, the attribution history, the precise transaction steps, the share rights and the owner’s broader succession and liquidity plans all need to be considered before documents are signed.
This article is general information only and is not tax or legal advice. The result of any estate freeze or refreeze depends on the specific facts, documents and applicable law.
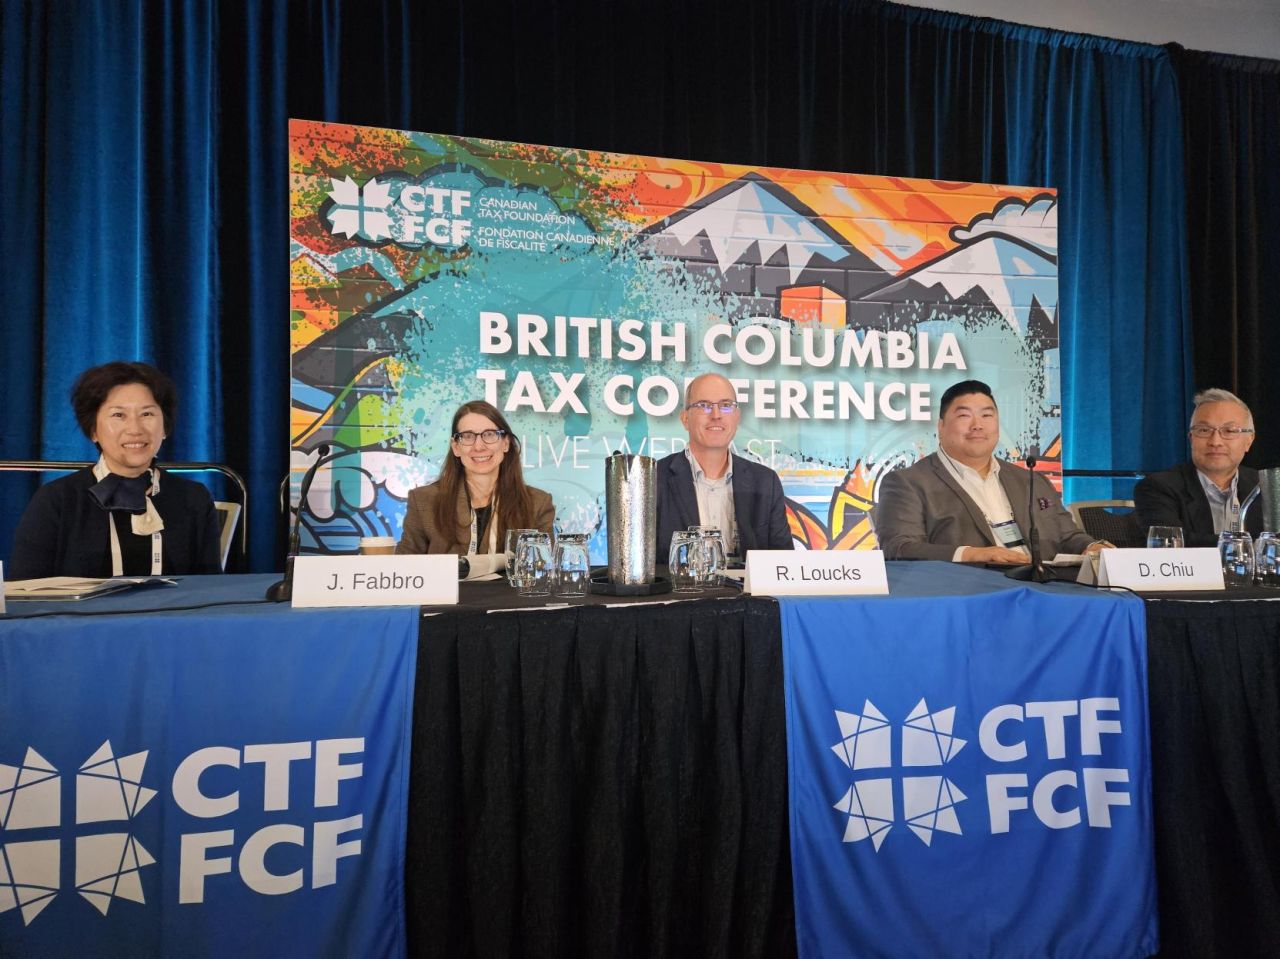
Adapted from “Tax Issues on a Refreeze of Company Shares,” co-authored by Raymond M. Loucks and Jessica L. Fabbro for the 2026 British Columbia Tax Conference.